I'm an Rcpp Believer
I didn't know.
I needed to draw from the multivariate normal distribution in R. I did what anyone in that situation would: I searched for an existing package that already had the functionality.
I heard snippets here and there from other graduate students. "R is inefficient." "Memory allocation is expensive." "You should just use C++." I didn't listen.
My MCMC sampler required me to make dozens of draws from the multivariate normal distribution. It was slow, but I suffered in silence. Better that than learn a new language, I told myself. The time that would take is much more than the time to just sit while the sampler ran.
Finally, while waiting days for a batch of tests to run, I peeked. I took a look at Hadley's chapter in Advanced R about Rcpp. It took a few days to figure out, days when my MCMC sampler continued to run. I couldn't believe the results.
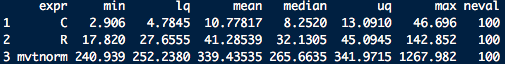
I was a fool. I was able to code portions of my MCMC in C++ easily using Rcpp Sugar. My sampling from the multivariate normal distribution became more efficient by a factor of 10. Life is better now. More vibrant. I can only hope to convince others in my position that the learning curve is not too steep, and that the payoff is worth it.
C++ Code
#include <RcppArmadillo.h>
// [[Rcpp::depends(RcppArmadillo)]]
// Sample N x P observations from a Standard
// Multivariate Normal given N observations, a
// vector of P means, and a P x P covmatrix
// [[Rcpp::export]]
arma::mat rmvnorm(int n,
                  const arma::vec& mu,
                  const arma::mat& Sigma) {
  unsigned int p = Sigma.n_cols;
  // First draw N x P values from a N(0,1)
  Rcpp::NumericVector draw = Rcpp::rnorm(n*p);
  // Instantiate an Armadillo matrix with the
  // drawn values using advanced constructor
  // to reuse allocated memory
  arma::mat Z = arma::mat(draw.begin(), n, p,
                          false, true);
  // Simpler, less performant alternative
  // arma::mat Z = Rcpp::as<arma::mat>(draw);
  // Generate a sample from the Transformed
  // Multivariate Normal
  arma::mat Y = arma::repmat(mu, 1, n).t() +
    Z * arma::chol(Sigma);
  return Y; }
R Code
my_rmvnorm <- function(n,mu,sigma){
  p = ncol(sigma)
  draw = rnorm(n*p)
  z = matrix(draw,n,p)
  y = (matrix(rep(mu,n),n)) + z %*% chol(sigma)
  return(y)}

print(summary(microbenchmark(C = rmvnorm(1,a_mean,a_cov),
  R = my_rmvnorm(1,a_mean,a_cov),
  mvtnorm = mvtnorm::rmvnorm(1,a_mean,a_cov))))
Results